How the changing face of wealth is reshaping private banking

As wealth becomes more diverse and financial lives more interconnected, Commonwealth Private says the value of private banking increasingly lies in understanding the whole picture.
BRANDVOICE – PARTNER CONTENT
Wealth rarely exists neatly in one place. Today’s private banking clients may include business owners, medical specialists, professional services partners and digital creators, including a new generation building wealth through emerging industries and those preparing to inherit family wealth.
For a business owner, personal borrowing may sit alongside property investments and an eventual business sale. Meanwhile, for the next generation, an inheritance can bring its own suite of decisions and responsibilities.
It is this growing complexity, the private banking arm of the Commonwealth Bank says, that is reshaping the face of private banking.
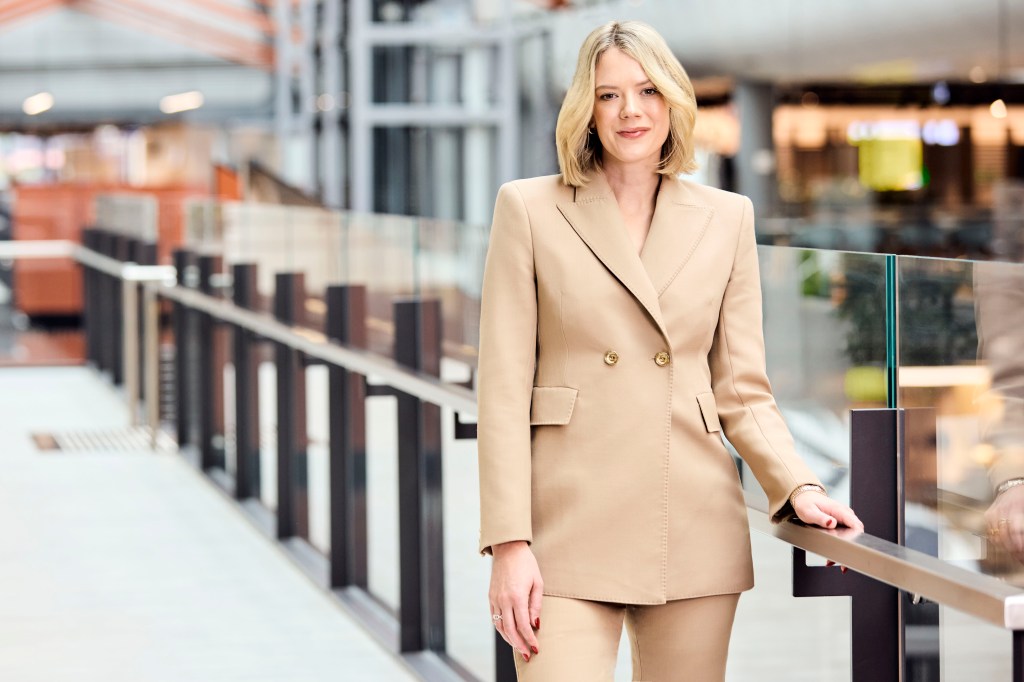
While wealth determines who qualifies for Commonwealth Private – eligibility requires more than $450,000 in household income and $2.5 million in investable assets – National General Manager Sarah Chadzynski, says financial complexity, rather than wealth or status, is often what brings clients to private banking.
“We think about it as the entry point because it’s usually where clients will have the level of complexity in their financial affairs where a private banker makes sense, and then they will usually need multiple layers of Commonwealth Bank services,” she says.
Seeing the whole picture
Private banking customers come from a wide range of backgrounds: professional services, such as lawyers, accountants and consultants; medical specialists; entrepreneurs and business owners; and those who have inherited their wealth. Some clients come from industries that barely existed two decades ago, such as YouTube content creators or game developers.
The real value of private banking lies in its ability to bring together expertise and support from across banking, lending and wealth through a single, co-ordinated relationship.
A business owner, for instance, might need commercial finance for their company while also investing for the future, managing property and taking out a home loan.
Chadzynski says clients want these needs treated as part of their overall relationship with the bank, not as separate products.
“Often, a client will have significant lending out for their business, and so we work really closely with that business banker, whether they are banking through our Major Family Group or Corporate and Institutional Banking divisions, to understand what their strategy is,” she says.
“We work really closely alongside that business banker and then put their personal finances into that perspective.”
Commonwealth Private also helps business owners plan the sale of their business or another liquidity event, including involving adult children as part of succession planning.
“If you are getting into that liquidity event and you haven’t got someone who’s thinking about what’s next for you, you are particularly susceptible to making reactive decisions,” Chadzynski says.
A business owner who has sold their company without a clear plan may face competing requests and advice, which can lead to reactive decision-making, or decision paralysis.
“Being able to have time to work through those circumstances early on, being clear on what they’re trying to establish and what they’re trying to do at that point in time, we find incredibly helpful,” Chadzynski says.
Professional services clients might have different needs. Many will have bought into a law or accounting firm and their financial affairs will have become more complex as a result of the partnership arrangement.
Trust remains personal
At the core of private banking is trust and expertise, built through the relationship between the client and their private banker.
Digital banking has made routine transactions easier, but Chadzynski says it hasn’t diminished the importance of the personal relationship. When clients are making major decisions – buying property, selling a business or planning for the next generation – they still want to speak with someone or work with a private banker who understands their circumstances.
“Even our most technically savvy clients still want to pick up the phone and speak to their private banker about some of these very deeply personal decisions,” she says.
“When we think about technology, we think about how that supplements the relationship and supports that experience.
“But for a private banking experience, it can’t ever truly replace that kind of one-to-one, really personal relationship where you build that trust.”
A new generation of wealth
Chadzynski points out that around $4 trillion in wealth is set to be transferred from baby boomers to their offspring in the coming years and 65% of that will go to women.
At the same time, she says the next generation is taking a more active role in shaping how family wealth is managed.
Clients have more information and expertise at their fingertips than ever before and it’s the role of the private banker to curate that information and help put them in the driver’s seat to make major decisions.
“We’ve got to get in and understand the children, the ecosystem, the other professional advisors, because there is a lot of complexity and governance in transferring money from current wealth holders to the next generation,” Chadzynski says.
“What are the family values? What is the plan for those assets? And what does the next generation want to do with that?”
Some clients planning for a wealth transfer bring their children into the conversation early, while others wait. Either way, Chadzynski says the transition involves more than simply the passing on of assets. It is also about stewardship: preparing the next generation to understand, manage and ultimately take responsibility for family wealth.
“What we need to understand is the decision-making style will definitely change. Particularly, a person who’s built the wealth will have a particular decision-making style and a strong sense of ownership. The next generation is obviously always wanting to make their mark and potentially branch out as well,” she says.
For ultra-high-net-worth families, this means working alongside accountants, family offices and other professional advisers to understand how the different pieces fit together.
“We form long-term relationships with families. We start out with the parents and often get to know the children through that intergenerational wealth transfer,” she says.
“As financial lives become more complex, private banking is increasingly about helping clients connect the different parts of their financial world.”
Chadzynski believes the value of private banking lies in “bringing together banking, lending and wealth expertise through a long-term relationship built on trust”.
For more information, visit Commonwealth Private
Want to see more Forbes articles on your feed? Tap here to make Forbes Australia a preferred source on Google.
Look back on the week that was with hand-picked articles from Australia and around the world. Sign up to the Forbes Australia newsletter here or become a member here.