The Nvidia-backed “AI factory” developer had planned a historic ASX listing. But Firmus’ IPO fell over days after it opened its book to investors. So, what went wrong?
Key Takeaways
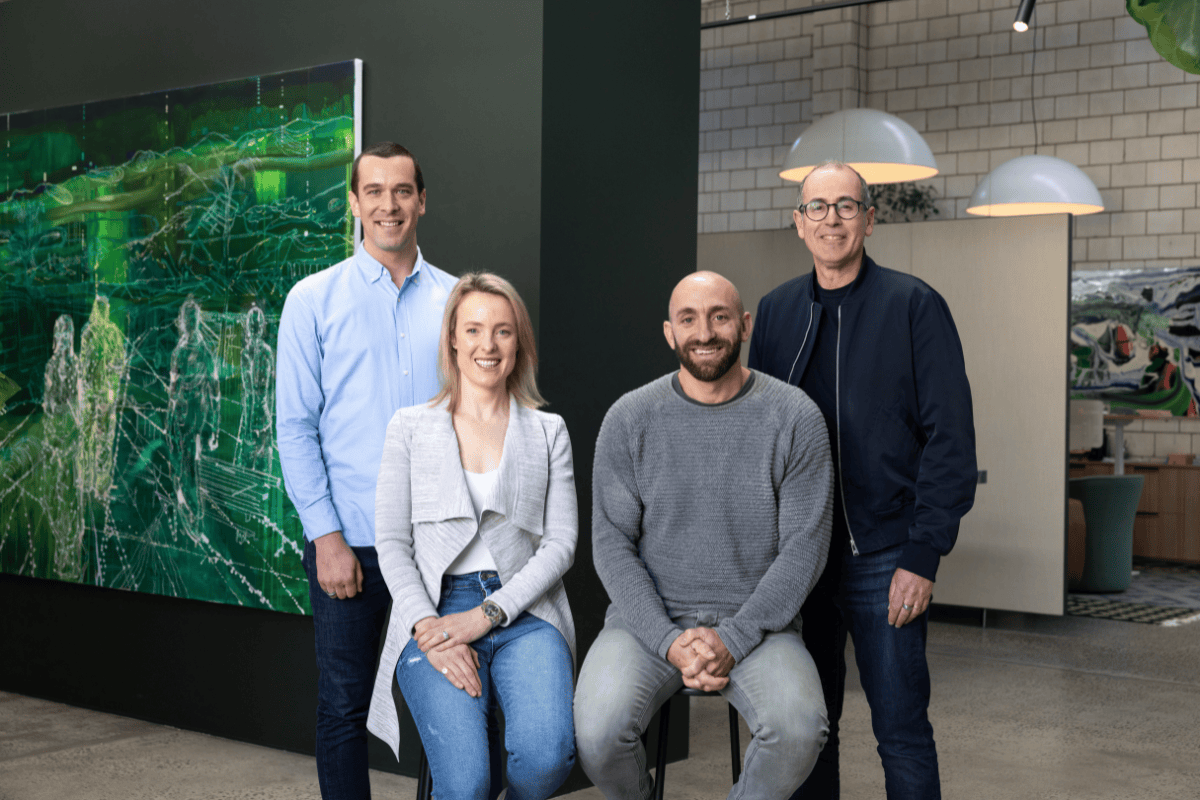
- Firmus, founded by Oliver Curtis, Tim Rosenfield and Jonathan Levee, withdrew its application to list on the ASX on Friday morning.
- The data centre developer will now look for private funding, likely from existing investors like Nvidia.
- Firmus offered shares at $11 to raise about $7 billion, at a market value of roughly $44 billion.
- The board said the terms on which the offer could proceed would not reflect the strength of the business, citing market volatility.
- Firmus was valued at $1.85 billion in September last year.
- Maas Group, which owns 3.2 per cent of Firmus and holds $1.2 billion in fit-out contracts has fallen 37 per cent over the past five days.
The Firmus IPO was always going to be one of Australia’s biggest tech and finance stories of 2026. By the time planning came reality, the company had raised billions of dollars and hoped to float with a market cap that would put it in the ASX 20. But with modest revenue and limited operating experience, there was uncertainty as to whether it could actually pull that off.
The sceptics, it turned out, were right – at least for the moment.
“Firmus has decided to withdraw its application to list on the ASX,” the company said in a written statement to media. “Firmus will now pursue capital from the private markets and consider alternative public and private market options.”
It capped a tumultuous week that saw Firmus stock offered to investors at $11 per share as the data centre company looked to raise $8 billion at a market cap of $44 billion. Interest was insufficient, leading to considerations that Firmus might lower its share price. Instead, it’s pulled the listing altogether.
“Confidence evaporated,” said Jun Bei Liu of investment firm Ten Cap. “It is disappointing for Australia not to have a listing like this, but I think it’s for the right reasons. It needs to be a bit more mature.”
Oscar Oberg of Wilson Asset Management, which invested in Firmus last September, conceded disappointment but said the company’s long-term prospects remain strong.
“We back the management team to deliver because they have so far,” Oberg said. “They’re aligned with one of the largest funds in the world and one of the largest companies in the world, so that gives you an added level of confidence in our view.”
Here’s how we got here.
What does Firmus do?
Firmus was founded by Oliver Curtis, Tim Rosenfield and Jonathan Levee as a Bitcoin miner in 2019, with its headquarters in Tasmania. But it soon thereafter pivoted to HPC – high-performance computing – striking up a partnership with Nvidia around 2021 that would prove instrumental in its rise.
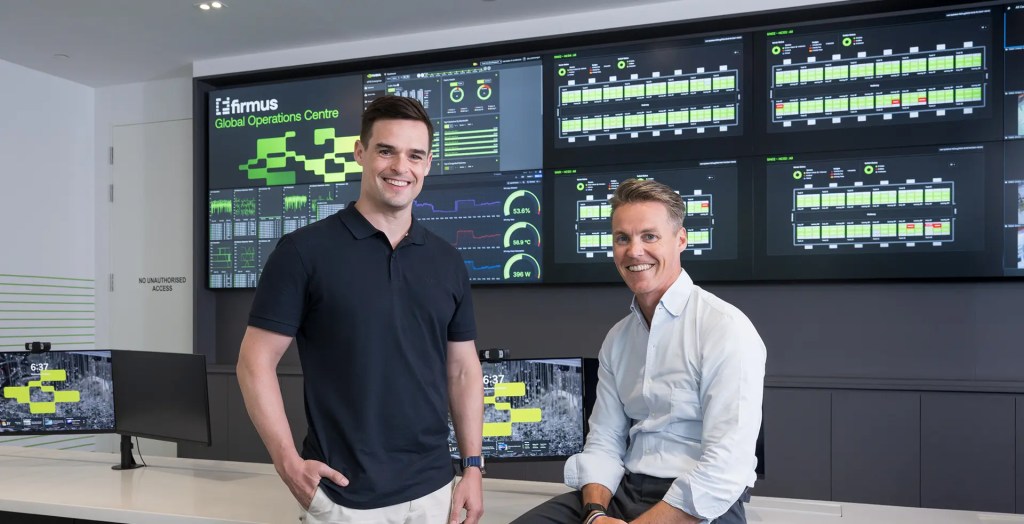
When ChatGPT launched in late 2022 and the world went bananas over AI, Firmus focused its efforts on “AI factories” – large data centres designed from the ground up to cater to the needs of Big Tech and other AI developers.
Firmus is what’s known as a “neocloud.” Traditional data centres supply infrastructure, electricity and cooling for customers, who provide their own processors and servers. Neoclouds instead buy their own chips – mostly Nvidia GPUs – and sell that compute capacity. Perhaps the most globally significant of the neoclouds is CoreWeave, which went public last year and is now worth US$45 billion.
Firmus combines these models, building its own data centres as well as providing customers with GPUs. Its special sauce is its HyperCube platform, which was designed with Nvidia, that it says integrates cooling, power and networking components of its facilities to provide compute at lower cost than competitors.
Why is this important for the ASX?
As we report in our latest magazine, the ASX has been shrinking over the past decade as listed companies are removed from the bourse via mergers, acquisitions from private equity or voluntary removal.
Though the ASX is home to companies with AI exposure, like Megaport and NextDC, it doesn’t have much in the way of a pure AI play. Much of that action is happening on New York’s Nasdaq exchange.
Firmus was slated to be the biggest IPO in decades, and would have provided the local exchange with a meaty new AI player. Whether or not the ASX is better or worse off without Firmus is likely to be a polarising debate as the AI boom plays out.
Why is it valued so highly?
The bull case for Firmus is roughly the following. Big Tech “hyperscalers” intend to spend US$800 billion on AI development this year, a number that will likely increase in the coming years. Energy consumption is the major operating cost associated with AI development – huge amounts of energy are required to power clusters of GPUs – and Firmus reckons it can cut that cost by up to 50 per cent.
OpenAI and Meta, two of the biggest AI developers in the world, are on board. OpenAI has signed on as the anchor customer of two facilities in Malaysia. Meta, meanwhile, has commitments in both Melbourne and Southeast Asia.
Last September Nvidia grew from a collaborator to an investor, backing Firmus during a $330 million funding round that valued it at $1.85 billion. It has invested twice more, in April and then again in August. That latter funding round valued Firmus at US$10.5 billion ($15 billion).
Nvidia holds a 7.2 per cent stake in the company, behind only Curtis’ 13 per cent and New York investor Coatue Management’s 8.4 per cent ownership. Blackstone owns 6.7 per cent of the company.
“The bull case is they’re [Nvidia] a large shareholder on the register and they’ve said publicly Firmus is all about their Asia strategy,” said Oberg. “If you don’t believe in Firmus, you don’t believe in Nvidia.”
It is hard to overstate the value of its relationship with Nvidia, struck when the chipmaker was merely worth US$150 billion – it’s now at US$5.5 trillion. It gives Firmus a leg up in procuring the tech giant’s chips, which are the most valuable commodity in the AI world. Firmus has secured access to 170,000 of Nvidia’s AI chips for its Indonesian facility.
Finally there is the scale of its proposed operations. It currently has 46 MW of operational capacity, 865 MW under development – and a huge 3.2 GW between planned capacity and growth rights. That is spread between Melbourne, Tasmania, Singapore, Malaysia and Indonesia. For comparison, total data centre capacity in Australia is somewhere around 1.5 GW.
Who founded Firmus?
The company was founded by Oliver Curtis, his cousin Tim Rosenfield and Jonathan Levee.
It has been a redemption story for Oliver Curtis, who became known in tabloid and corporate circles a decade ago for an insider trading scheme that landed him in prison.
Between 2007 and 2008 Curtis, an investment banker at Transocean Group, conspired with then-friend John Hartman to use information gleaned from the latter’s job at $6 billion fund manager Orion to make plays ahead of Orion’s market-moving trades. The pair made approximately $1.4 million from the exploit.
Curtis was convicted in 2016 and sentenced to two years, but ended up serving only one.
“What has been a great focus for me is to ensure the legacy is not one of that past, but the legacy is of the future,” Curtis told Rampart in a rare interview earlier this year. “Redemption is an absolutely essential part of chapter two, because we’re probably only at chapter two as far as I’m concerned.”
Oliver’s father is Nick Curtis, a former Macquarie banker and executive chairman of Lynas Rare Earths. After investing early, Nick owns 5.6 per cent of Firmus.
So, what went wrong?
Firmus’ bankers opened its book to investors on Tuesday, offering the company up for $11 a share, with the hopes of closing the IPO by Friday. But there wasn’t enough interest from local super funds and fund managers, meaning they would either have to cut the price of their shares or walk away from the float.
Half of the IPO allocation would have gone to early backers, allowing them to stock up on shares. But they could also do the opposite. Investors with large holdings are usually restricted from offloading their shares for a period of time after a company lists. That only applied to roughly 42 per cent of Firmus’ shares. Its backers could sell large chunks of their stock the second trading opened.
Considering how high Firmus’ valuation has shot up in such a short period of time, from under $2 billion last September to a proposed $44 billion, that was evidently a red flag.
“My view is that it should be [offered at] less than $10 billion valuation,” Liu said when asked about a fair IPO price.
Then there is the more fundamental issue of revenue. Firmus’ contracted revenue is in the billions, but it only starts to collect that once its facilities are live. Annual revenue for last year was $50 million.
“Investors just weren’t prepared to pay a sky-high price up front for capacity that’s still largely on the drawing board,” said Josh Gilbert, analyst at eToro. “With so few ways to get AI exposure on the ASX, Firmus had rarity value on its side, but investors here and offshore made it clear that scarcity alone won’t get them to pay up.”
Firmus, for its part, said reducing its asking price would not reflect its growth potential.
“The Board therefore concluded that proceeding with the Offer was not in the best interests of the Company and its shareholders,” it said in a statement.
Want to see more Forbes articles on your feed? Tap here to make Forbes Australia a preferred source on Google.
Look back on the week that was with hand-picked articles from Australia and around the world. Sign up to the Forbes Australia newsletter here or become a member here.